 Rukhsar Khundmiri
IOU Financial · Mobile Loan Application
Rethinking how small businesses apply for funding
The application needed to collect more information and introduce verification while keeping qualified applicants moving toward submission.
- Role
- Sole product designer
- Team
- Product and Engineering
- Timeline
- Nov 2025 to Feb 2026
- Status
- Live, with ongoing iteration!
Open the interactive case study
Overview
IOU needed to collect more applicant data and add verification while keeping qualified applicants moving toward submission.
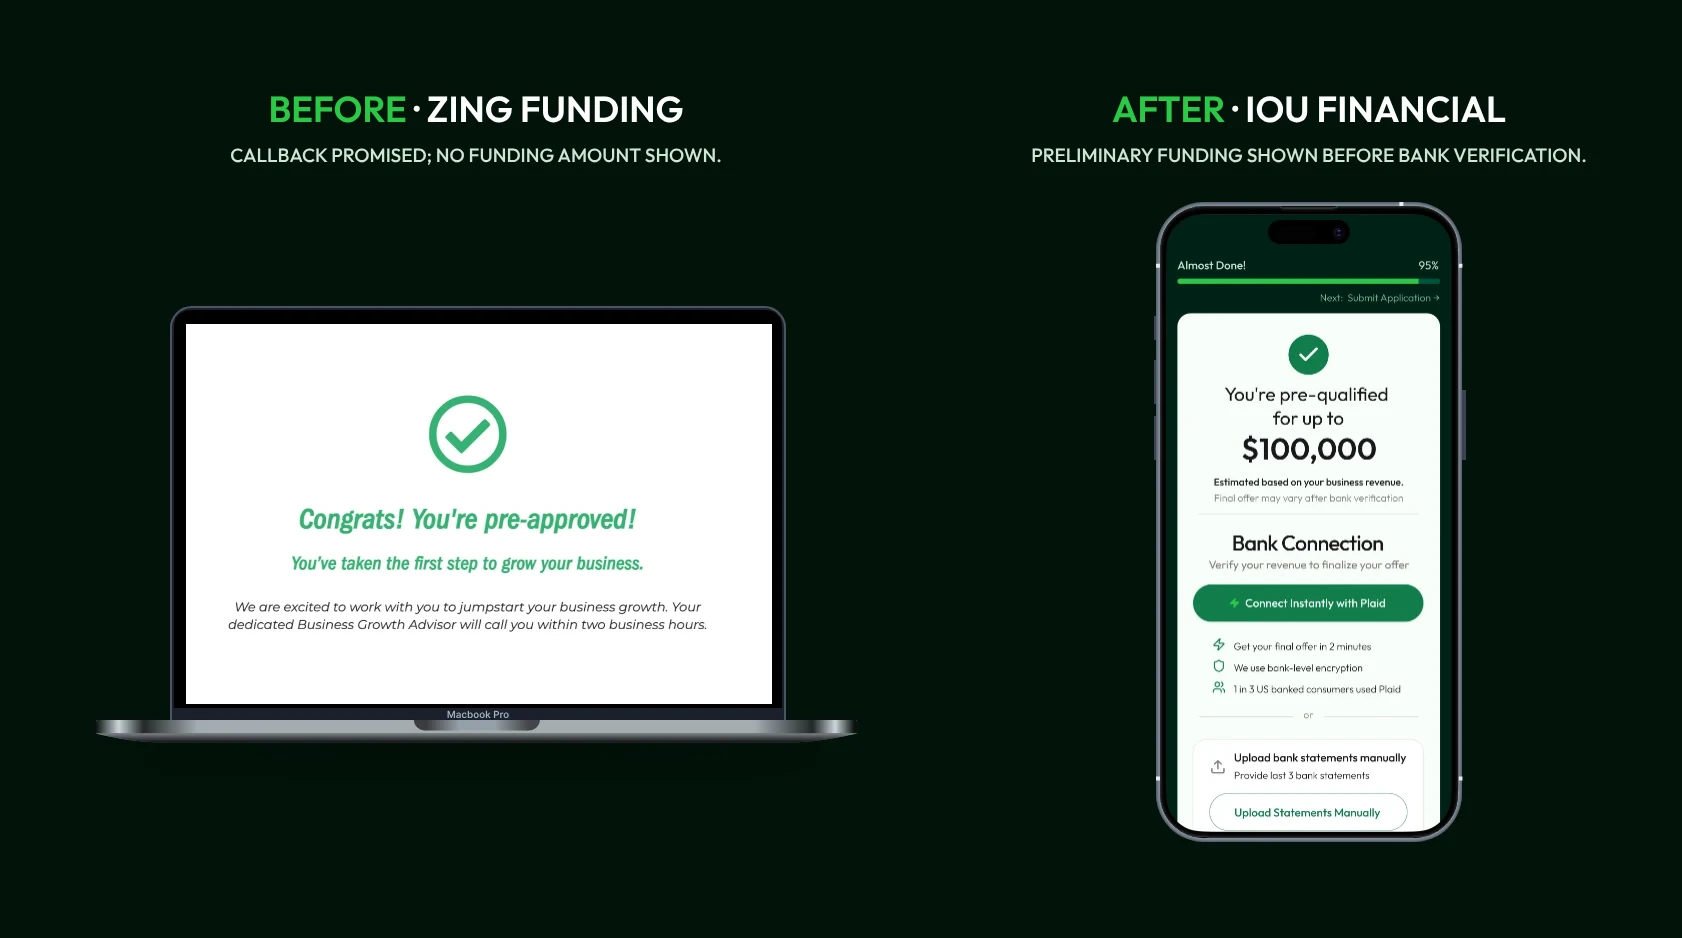
Following the Zing Funding merger, IOU’s loan application still used the previous brand and ended with an advisor callback. New requirements called for earlier eligibility screening, more applicant data, account creation and email verification, and a bank-connection option. Device tracking made mobile the priority.
As the sole product designer, I worked with product and engineering to translate these requirements into the application’s information architecture, screen layouts, and mobile interactions, using IOU’s new visual identity as the foundation.
What Shipped
A mobile loan application that takes small businesses from eligibility checks through verification and submission.
Launched in March 2026, the application checks eligibility, collects business and personal details, and guides qualified applicants through verification. A preliminary funding amount appears before bank connection, with statement upload available as an alternative.
After submission, the confirmation explains that bank data is being reviewed and a final offer will follow by email.
Flow Decisions · Tradeoffs
The full flow, flow decisions and tradeoffs are password protected.
Need the password? Email me
Mobile Design & Exploration
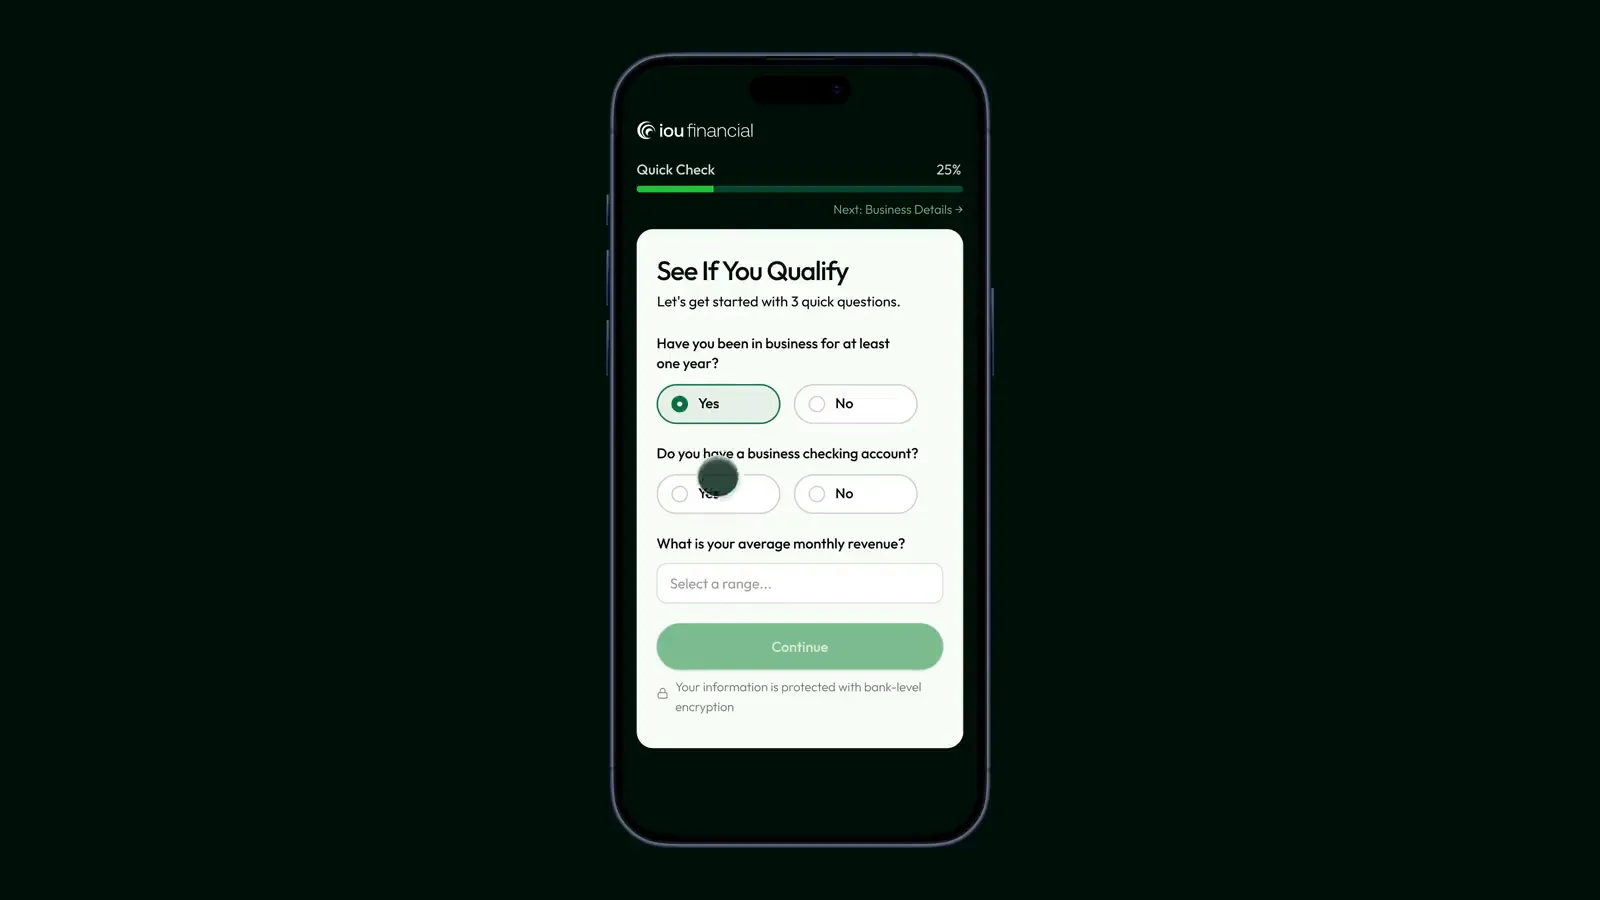
Make each mobile step easier to navigate, with focused selections and a clear preview of what comes next.
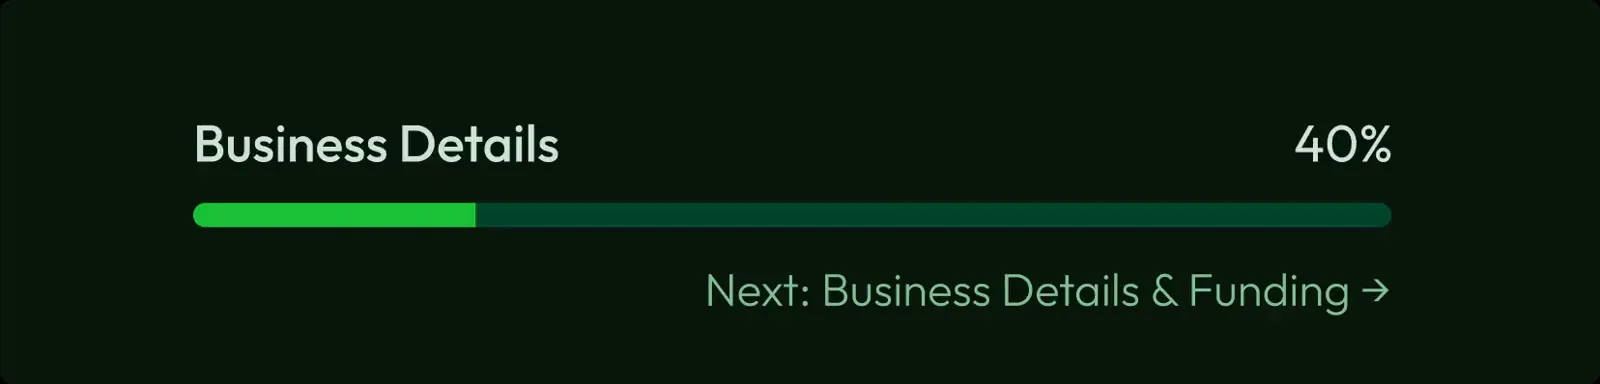
Named stages and next-step previews orient applicants throughout the application. The percentage indicator represents progress through the stages rather than estimated completion time.
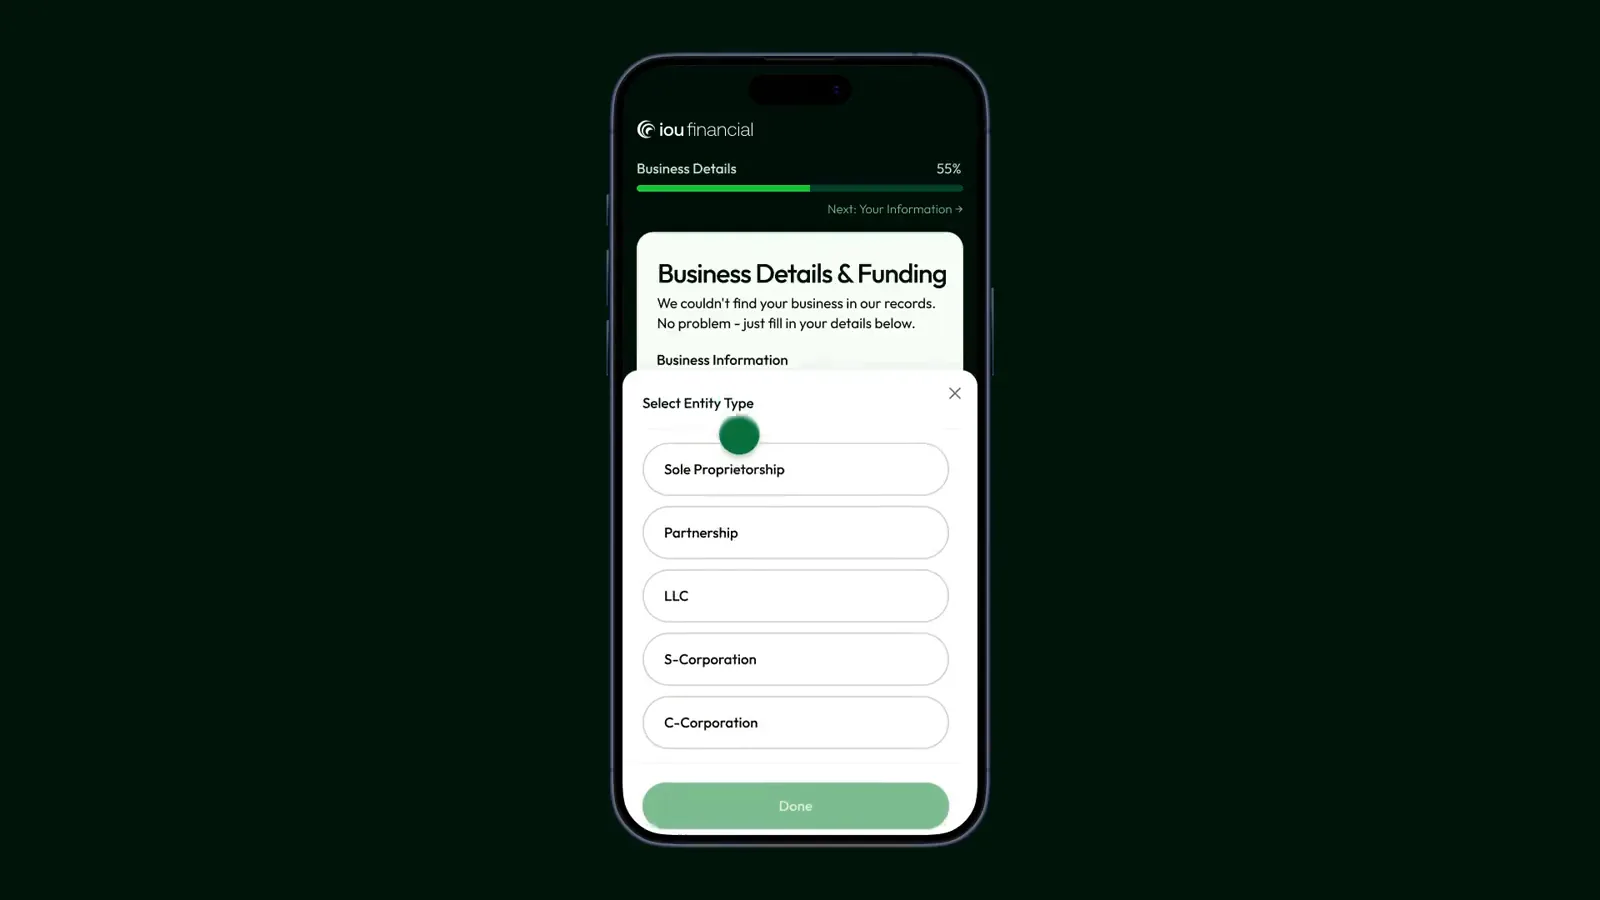
Device tracking made mobile the priority. Bottom sheets, panels that open from the bottom of the screen, keep selection lists separate from the form and give options more room. Large tap targets support touch interaction.
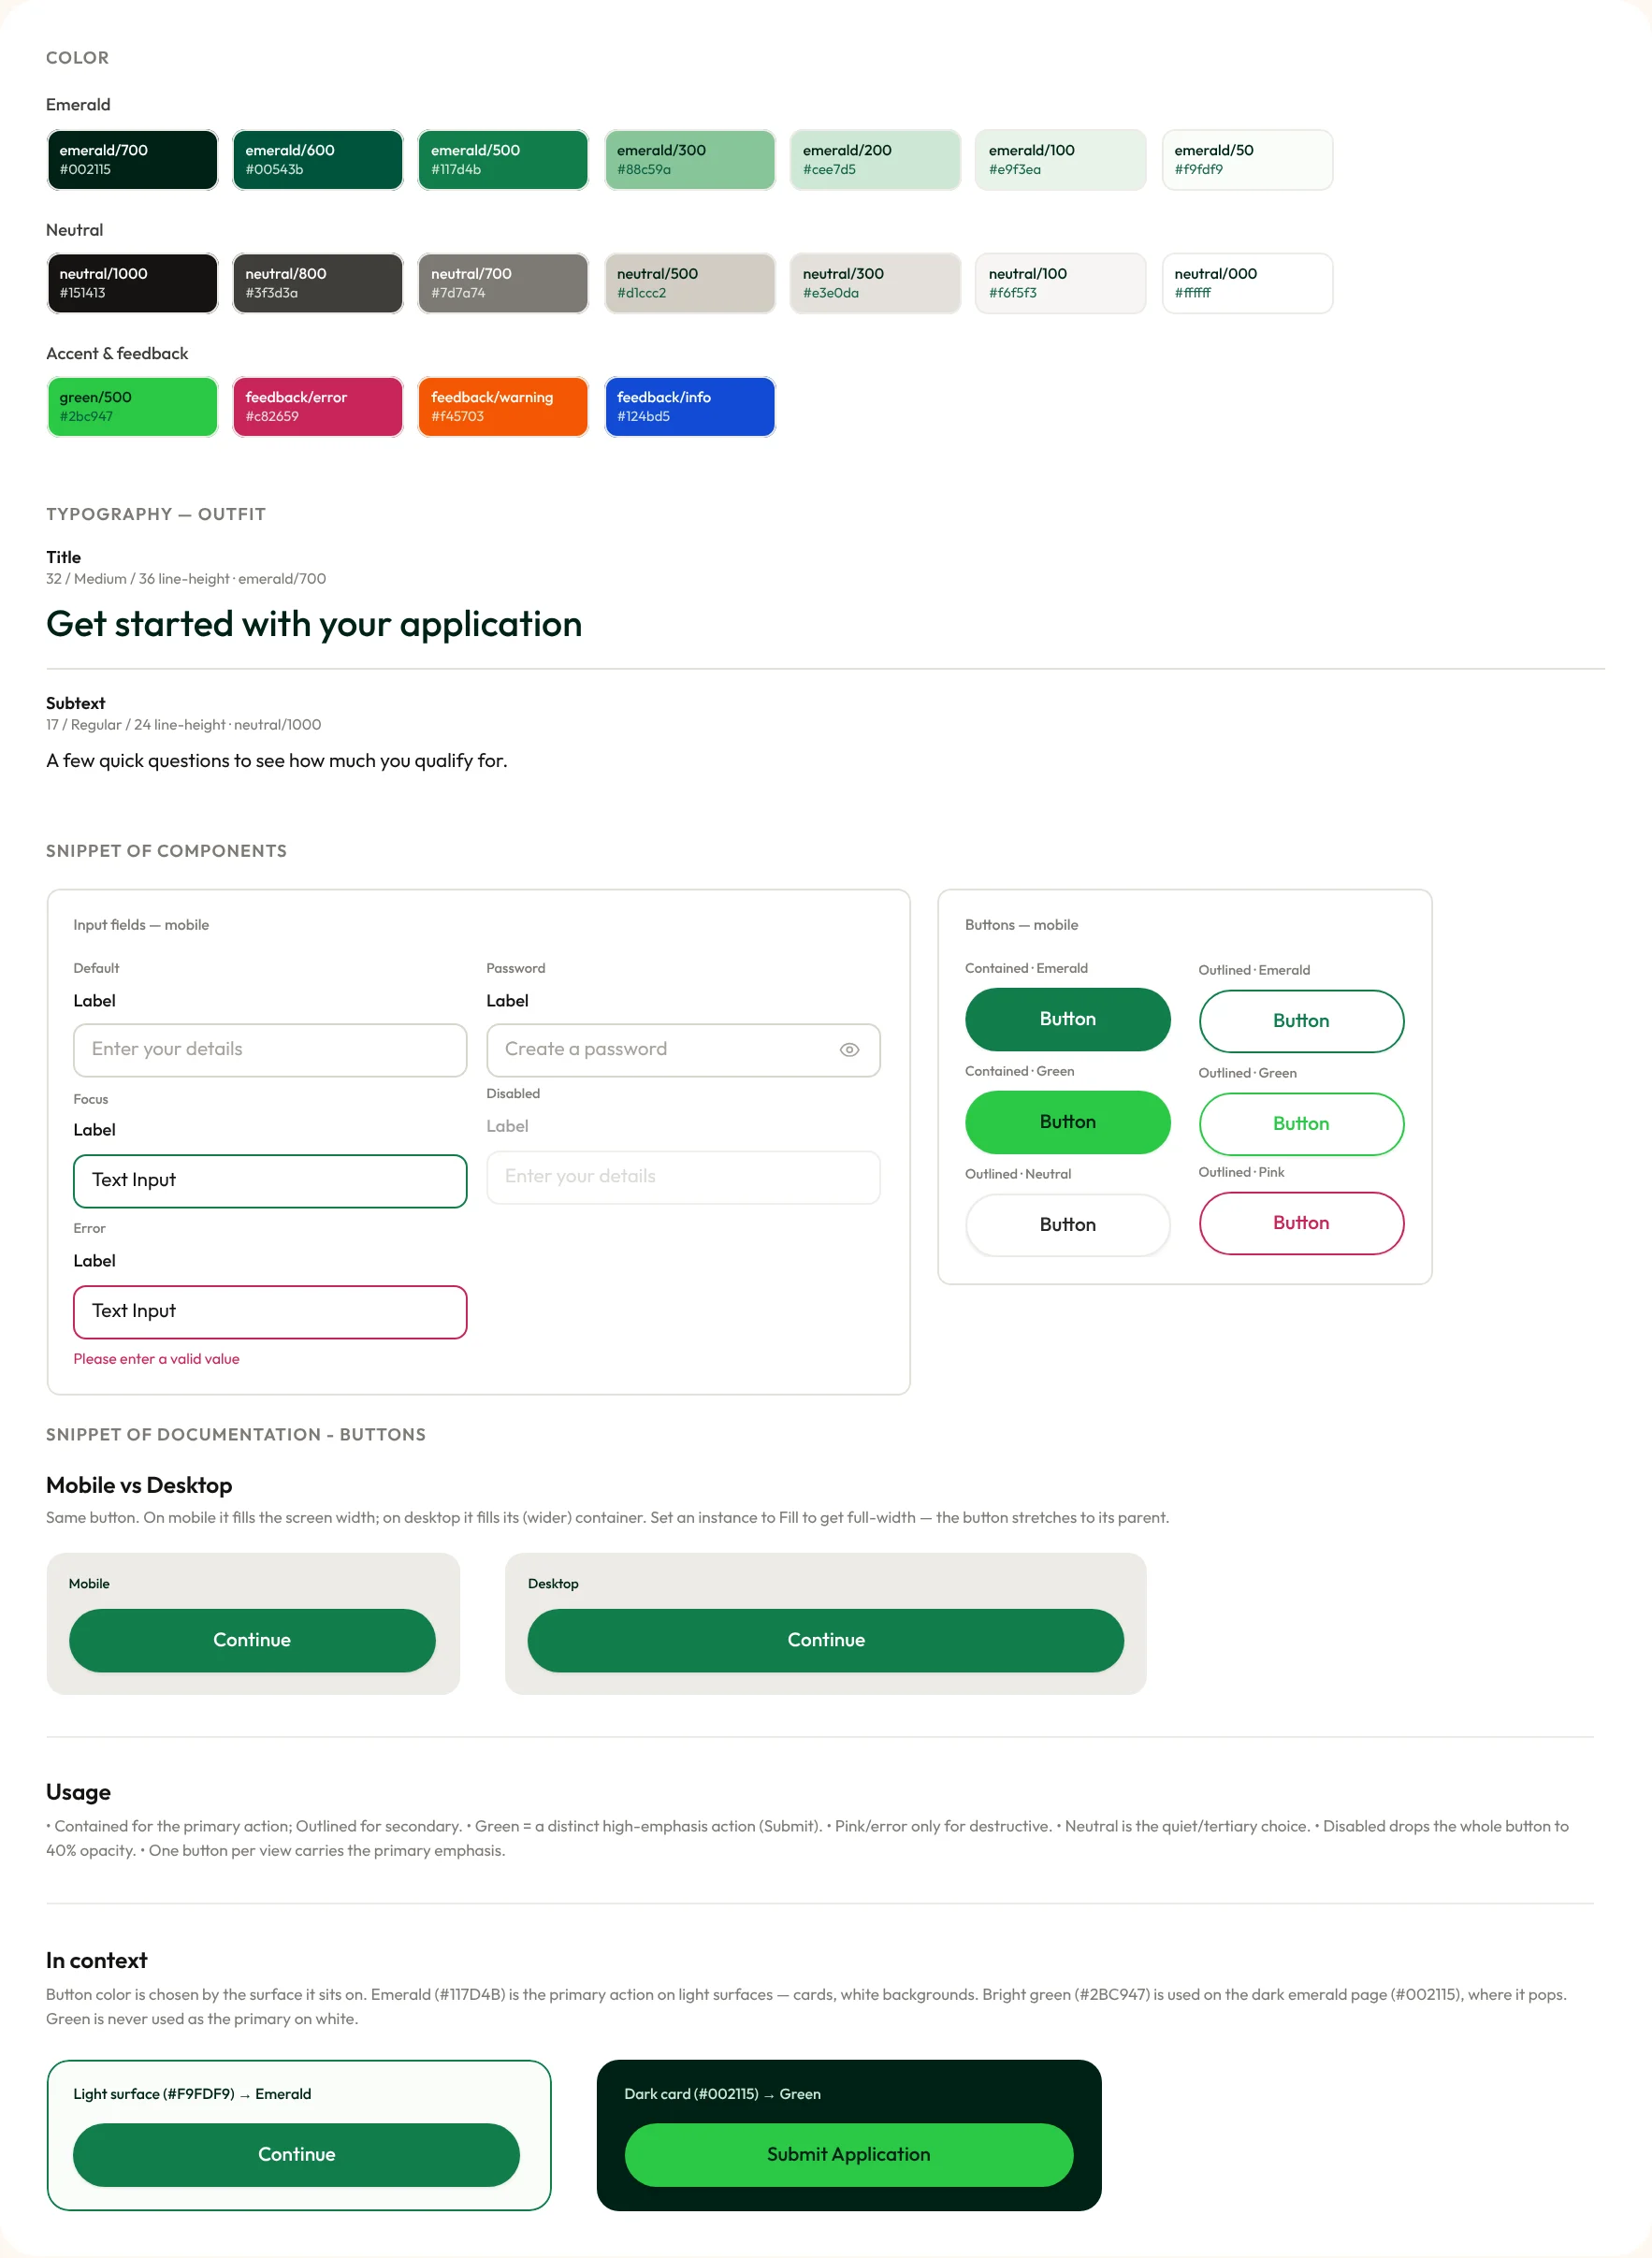
AI tools helped expand and document the system’s components, states, and usage guidelines, creating a reusable foundation for the loan application and future customer experiences.
Live Results
Production data revealed how merchants moved through the application and where to investigate next.
- 57%
- Qualified conversion
- 6m 14s
- Median tracked completion
- 81%
- Mobile device share
The April 28 review reported 57% qualified conversion for the previous week, a median tracked completion time of 6 minutes 14 seconds, and 81% mobile device share across the reporting windows reviewed.
The previous application lacked comparable tracking beyond its first page. Ad spend and lead quality also changed during launch, so these figures describe production performance without isolating the redesign’s impact.
The review exposed a tracking gap: some logged-in returnees skipped email verification and were excluded from the full tracked sequence. Understanding that limitation is part of interpreting the drop and deciding what to investigate next.
Reflection
What I learned
An established brand still leaves the experience to design.
The website gave me a visual foundation, but the application needed its own sequence, explanations, and interaction states. Most of my work went into translating business requirements into a flow merchants could follow.
Prototypes helped me explore; real behavior guides iteration.
AI-assisted prototypes reduced manual production work. Synthetic reviews raised questions about possible friction, while production data provided evidence of how merchants moved through the application.
The next iteration starts with verification and progress.
I want to understand the email-verification drop and account for the tracking gap before choosing a fix. I also want to revisit whether the phased progress bar sets accurate expectations about the work remaining.